
Susan
Edmunds Money Correspondent
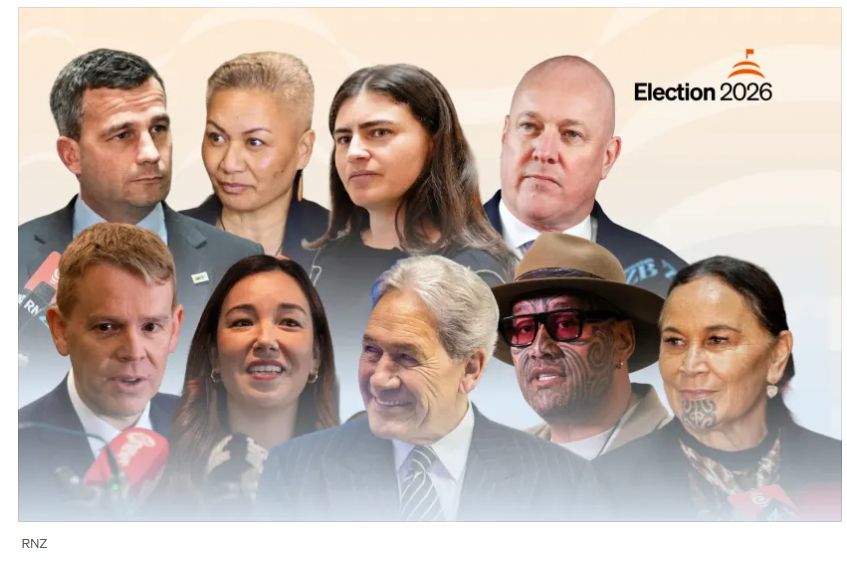
Political
parties have revealed policies over the past weeks that are
likely to affect household budgets, should they take
effect.
We’ve compared a few scenarios to show how
that might look for different sections of
society.
These are only for illustrative
purposes.
Scenario 1: Retired couple
Freehold
home: $2 million
Land value: $1.1 million
Other
income: About $15,000 a year on top of NZ Super, in one
person’s name.
No children in their
care
National
At the moment, this couple’s
basic financial position would be broadly unchanged under a
future National government.
Finance Minister Nicola
Willis has said National will campaign on some tax policies
and has hinted that she wants to see tax brackets change,
but also said that would not be appropriate, until the books
were back in surplus.
Labour
A capital gains
tax might register as an issue for this couple, but their
family home would be exempt from Labour’s proposed 28
percent capital gains tax, because it only applies to
residential investment and commercial property.
They
would have access to up to three GP visits a year and free
prescriptions for fully funded medicines from next
July.
Opportunity
Advertisement – scroll to continue reading
The retired couple are the
most affected by Opportunity’s policies of any scenario we
modelled.
They would have to pay 1.75 percent annual
urban
land value tax, which would be about $19,250 a year for
this property, although Opportunity says they could defer
the tax until the property was sold.
Opportunity
proposes a $19,400-a-year Citizen’s Income for each eligible
adult and this would be topped up so that superannuitants
received the same amount they currently get from the
pension.
Green Party
This couple’s home is
well below the Green Party’s $20 million wealth threshold
for a couple, so there would be no wealth
tax. They could also benefit from the Green Party’s
$10,000 tax-free income band.
The Greens do have a 33
percent capital acquisitions tax in their policies, which
would apply to inheritances above $1 million, with
exemptions for family homes and farms. If the couple did not
have children to pass the home to, the tax could apply to
their estate.
The Greens could leave them about $2769
a year better off.
Te Pāti Māori
This couple
would be below the $4 million wealth tax exemption proposed
by Te Pāti Māori for a couple, provided they have no other
substantial assets.
Te Pāti Māori proposes no tax on
income up to $30,000, 15 percent from $30,001 to $60,000 and
higher rates above that. That tax change would leave them
about $7809 a year better off.
A 5
percent stamp duty could matter, if they sold the home.
On a hypothetical $2 million sale price, the gross amount
would be $100,000. This is usually paid by the
buyer.
ACT
ACT has a goal of a two-rate
income-tax structure, with a top rate of 28 percent. Its
announced health
policies could affect this couple indirectly, through
greater Pharmac funding and expanded pharmacist
treatment.
NZ First
If one person was not a
citizen, they could lose access to NZ
Super from 2029.
Scenario 2: Young
first-home-owning family
House: $900,000
Land
value: $600,000
Mortgage: $800,000
Children: Two
of primary-school age
Income: One person earns
$100,000 and the other $50,000.
National
If
they had not already bought their home, this couple could
benefit from National expanding the First
Home Loan scheme, which allows purchasers to have a
deposit as low as 5 percent.
National proposes to make
this available to people earning up to $300,000 combined,
twice the current level. At the moment, some people earning
about $150,000 a year have to be careful their income does
not exceed this limit, so they can still access the
scheme.
If they had another child, National’s plan to
extend paid parental leave to 30 weeks could
help.
National would make KiwiSaver
compulsory from 2028, with contributions increasing to a
combined 12 percent by 2032, which might reduce their
take-home pay, but mean they saved more for
retirement.
Labour
Their family home would be
exempt from Labour’s CGT. The household could receive three
free GP visits each and free prescriptions for fully funded
medicines.
Labour also proposes compulsory employer
KiwiSaver contributions, eventually reaching 6 percent, even
if an employee reduces or pauses their own contribution.
That could be valuable in a household where money is tight,
or someone is working part-time and cannot afford to make
employee contributions.
Opportunity
The
family’s annual land tax would be $10,500 a year, but the
couple could also potentially receive two citizen’s incomes
of a combined $38,800 a year.
Opportunity would also
replace the current income-tax scale with rates of 28
percent up to $50,000, 34 percent from $50,001 to $200,000
and 39 percent above $200,000. Existing Working for Families
or other payments might also be affected.
The
household could be about $13,836 a year better
off.
Opportunity also has a compulsory KiwiSaver
scheme, eventually involving 6 percent employee, plus 6
percent employer contributions.
Green
Party
The family would not be subject to wealth tax
and would benefit from the tax-free first $10,000 of each
adult’s income. The higher earner could eventually move into
the Green Party’s top tax rate of 45 percent on income over
$160,000 a year.
They would be about $1086 a year
better off.
Te Pāti Māori
The lower earner
may be able to access the Income Tax Kai Credit, which is
available to adults earning $60,000 or less. The party
describes it as worth up to the equivalent of eight weeks of
food each year.
Because they are first-home buyers
purchasing a house worth less than $1 million, they would
not have had to pay stamp duty.
The tax change would
make them about $9236 a year better
off.
ACT
ACT’s long-term lower and flatter
income-tax model could reduce their income tax, particularly
for a higher-earning partner.
The couple would benefit
from ACT’s proposal to remove tax on KiwiSaver earnings.
This would allow their balance to grow more quickly over
time.
NZ First
If they had more children, they
would benefit from NZ First’s Kiwi Kids Grant, of up to
$5000 per child per year for three children.
New
Zealand First also proposes automatically enrolling newborn
New Zealand citizens in KiwiSaver, with a $1000 government
contribution. That would not apply retrospectively, so the
existing children would not benefit.
Scenario 3:
Single 55-year-old apartment owner
Apartment value:
$750,000
Mortgage: $200,000
Income: $85,000 a
year
National
There would be no major change
for this household, unless National was able to progress its
tax plans.
Labour
The apartment is the
person’s family home, so it would be excluded from Labour’s
CGT. Their direct benefits could include three free GP
visits per year, free prescriptions and potentially higher
compulsory employer KiwiSaver
contributions.
Opportunity
The amount of land
tax due would depend on the share of the underlying land
value that the apartment owner has. They could receive the
$19,400 Citizen’s Income, offset by the new income-tax scale
and the land tax.
Green Party
They would gain
from the tax-free threshold and could be about $553 a year
better off. The $10,000 tax-free band saves about $1000 a
year in tax, but the Greens would increase higher tax
brackets.
Te Pāti Māori
If they sold the
apartment for $750,000, the headline 5 percent stamp-duty
amount would be $37,500, unless the buyer was a first-home
buyer. They might save income tax on the new schedules of
about $5000 a year.
ACT
The apartment does not
attract an ACT wealth or capital-gains tax. A lower, flatter
income-tax structure could reduce their tax bills.
The
person could benefit from any move to remove tax on
KiwiSaver earnings.
NZ First
No major impact,
unless they own a business with turnover below $30 million,
in which case the tax rate could drop from 28 percent to 30
percent.
Simplicity chief economist Shamubeel Eaqub
said it was important to note that tax, spending, investing
and borrowing were all linked, and it was not possible to
make one change and keep everything else constant. A change
in tax revenue, for example, would necessitate changes in
spending.
He said, on the PREFU track, health baseline
spending would fall in real terms by 2031, unless future
Budgets topped it up.
Westpac chief economist Kelly
Eckhold said it was hard to take any policy at face value,
because every party would face trade-offs, as it went into
negotiations.
“The problem with all of this is they
are saying what they would do if they were in charge, but no
single party is going to be in charge.”
Recent years
had shown how the global environment could change the
domestic picture.
He said there seemed to be an
increasing focus around the world on fiscal sustainability,
which was showing up in bond prices.
“For a country
like New Zealand, that’s something to keep in
mind.”
Higher bond rates were more expensive for the
government to manage, he said, and would flow through to
higher long-term interst rates for New Zealand
households.
New Zealand’s public broadcaster, providing comprehensive NZ news and current affairs, specialist audio features and documentaries.
Radio New Zealand is a Crown entity established under the Radio New Zealand Act 1995. Radio New Zealand News are vital elements in our programming, providing impartial news and information to New Zealanders every day. Radio New Zealand (RNZ) provides listeners with exciting and independent radio programmes in accordance with the Radio New Zealand Charter.

